
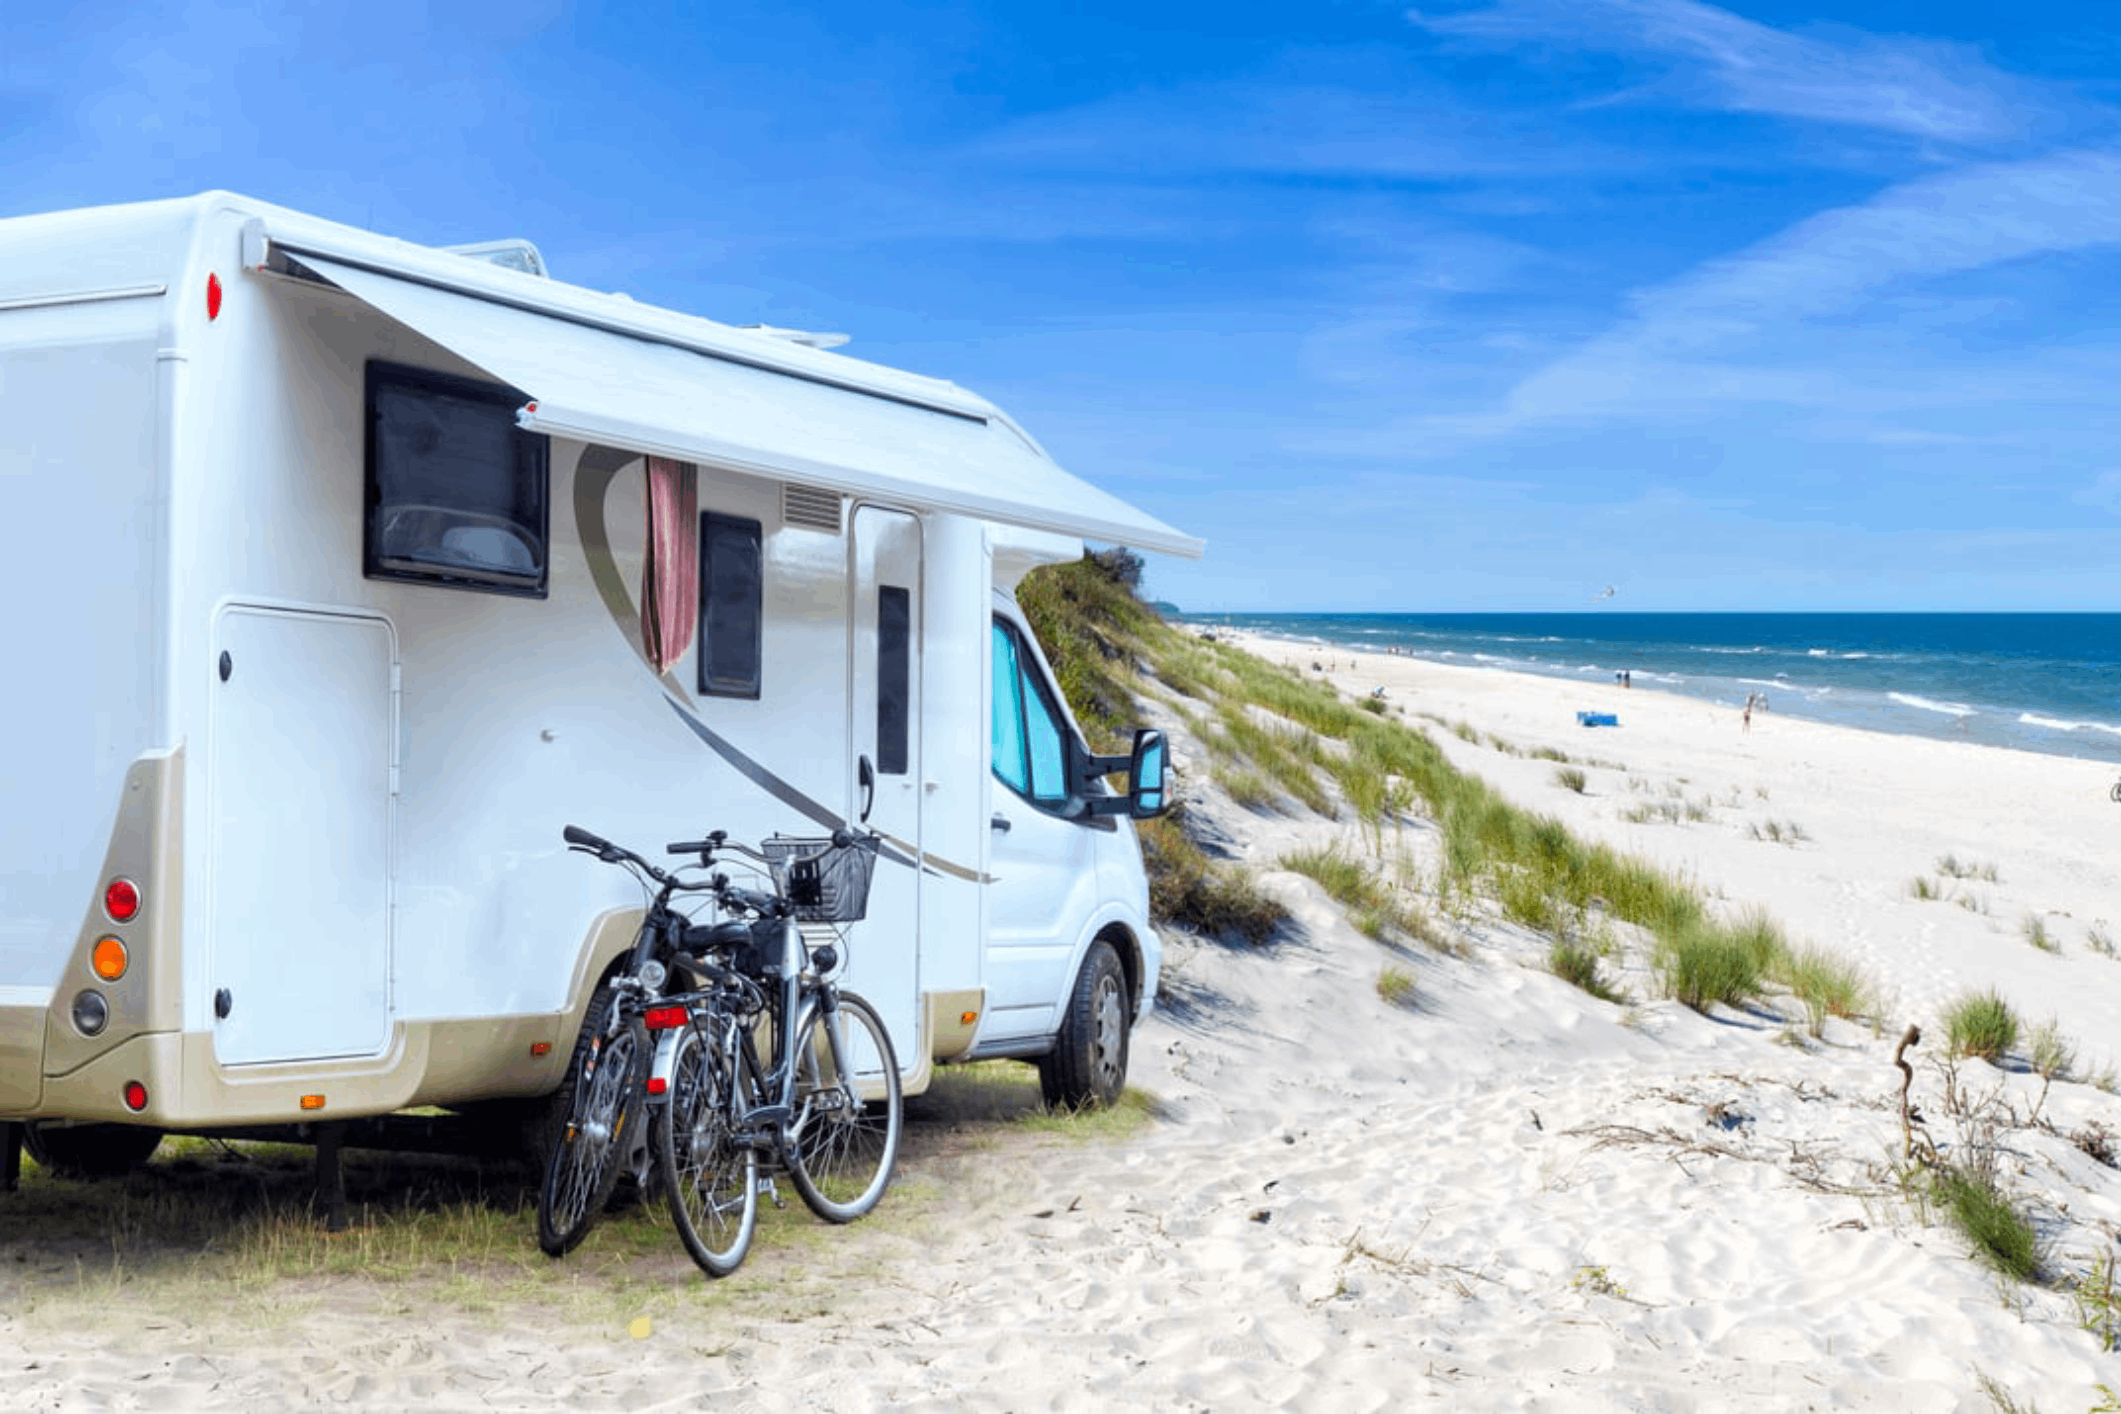
Caravans capture the New Zealand imagination. Whether you’re someone who grew up with a family caravan by the sea for summer holidays, or you’re coming to it later in life, there’s something about the freedom of caravan ownership that appeals to a lot of us.
There are about 120,000 towed caravans and trailers registered in New Zealand. There was a surge in interest around the time of the pandemic, but registration data shows demand has settled back to more normal levels.
If you’re thinking about buying your first caravan, you might be wondering about your options. What sort of caravan will work for your family? What is likely to be the best way to achieve your holiday dreams, whether you’re planning to travel locally or further afield? Buying new or used can make sense, depending on how much you want to spend and how much you plan to travel.
Getting your finances sorted before you go shopping for a caravan can make the whole process easier, and it means you have an idea from the outset of what you should be able to spend. That could reduce the chance you’ll fall in love with something that’s a bit out of your price range and end up disappointed.
Here are a few things to think about as you start the process.
Should you buy a new or used caravan?
There’s no right answer to this question. A new or used caravan can be a great option, and it will come down to your budget, how you travel and how long you plan to keep your caravan. You’ll need to think about the purchase in a wider context.
How to tell if switching could save you money

Buying a new caravan
When you purchase a new caravan, you’ll usually get a manufacturer warranty, which should mean you won’t have to spend anything on repairing or replacing covered parts in the early years of ownership. That can be a benefit when it comes to managing your budget. You should have less maintenance to worry about with a new caravan, anyway, and you may also get all the latest safety features and modern layouts. But you’ll also usually pay a higher purchase price. There may be a faster rate of depreciation to consider too, because new vehicles generally lose their value fastest early in their lives.
Buying a used caravan
When you buy a caravan secondhand, you’ll usually pay a lower purchase price, and some of the most significant depreciation may already have happened. You may be able to buy a caravan that offers better value for money, and you may find there is a wider range of caravans available to choose from in your budget. Depreciation is usually slower on secondhand vehicles, but the repair budget can be more unpredictable. If you’re buying secondhand, conducting a thorough inspection is important. There can be problems lurking that you can’t see at first glance.
It may be the case that lenders will offer a shorter loan term on older caravans, which means you may pay higher weekly or monthly repayments, even if the overall loan amount is less than a newer model.
Which option is right for you?
If you’re trying to decide what option is likely to be the right one for you, you might need to consider a few things.
Your budget:
What can you afford to pay for your caravan? When you’re weighing this up, you’ll need to consider what you can afford to pay in regular repayments, as well as the upfront purchase price.
How often you’ll travel:
How much use do you think you’ll get out of your caravan, and how many kilometres do you think you’ll travel? Someone who plans to travel a long way each year may decide it makes more sense to pay a little more upfront.
How confident you are with maintenance:
Sometimes, maintenance on a secondhand caravan can be the sort of thing that can be tackled at home by someone with the skills to do so. But if you’re not comfortable with that, and you don’t want to have to budget to pay someone else to handle repairs, you may prefer to buy a newer caravan that should require less work in the early years.
The features you genuinely need:
New caravans can come with a range of high-tech features and modern layouts. These can be impressive and make an impact when you’re shopping, but how many will you and your family really need? It may not be worth paying more for features you won’t often use.
How long you plan to keep the caravan:
If you think you’ll only own the caravan for a short time, you may be more concerned about how fast its value will drop. New caravans can depreciate more quickly early on, as any new vehicle does. Depending on your plans for the caravan, this may be a consideration.
Set your budget before you start shopping
The purchase price may be what you focus on when you’re shopping for your new caravan, but it’s just one part of the overall cost of ownership.
Your one-off costs
Some things you’ll only pay once: The purchase price, or your deposit, if you’re financing the purchase. Towing equipment, including a tow bar and possibly a brake controller. A pre-purchase inspection to make sure everything is in order.
What you pay every year
Then there are costs that will keep coming: Your loan repayments, if you’ve financed the purchase. Your insurance. Registration and licensing. Regular warrants of fitness for the caravan itself and the vehicle that tows it. Storage, if you can’t keep it at home. Maintenance and repairs and holiday park fees.
Will your car actually tow it?
A key consideration for any potential caravan purchaser is whether their vehicle can actually tow any caravan they are considering buying. You’ll need to check your vehicle’s braked towing capacity in the owner’s manual to work out how much you can safely tow. There are legal requirements here that are important to be aware of.
You’ll need to compare that towing capacity to the weight of a caravan when it’s fully laden, not when it’s empty. Things like water, fuel and the gear you want to take on holiday can all add weight quickly. You’ll also need to find out what tow ball weight your vehicle can handle. If you tow more than your limit, you may find your insurance won’t cover you if things go wrong.
Should you arrange finance before you start looking?
Getting your finance in order before you start looking for a caravan could change the way you shop. A pre-approval gives you an indication of what a lender is likely to be comfortable lending you, so you know what caravans you can actually buy.
This can mean you don’t get into a scenario where your heart is set on a certain vehicle only to discover the finance doesn’t line up.
Working on the loan application before you go shopping also means you’re in a position to compare your finance options calmly. You’re not emotionally invested in making a purchase happen, so you can take your time to find the right solution for you.
Pre-approval also means you’ll know what your repayments will look like in your budget, and it can put you in a stronger position with a private seller because you’ll be able to act quickly if you find the caravan you want to purchase.
What do lenders look at when financing a caravan?
Many of the things that lenders look at with a caravan finance application are the same as with any personal loan application. The lender will look at your income and your employment to see whether you have enough money coming in to service your loan. They will also look at your existing financial commitments to check there’s room for a new loan in your budget, and your credit history to get a sense of how likely you are to repay your loan.
The loan amount you’re applying for and the deposit you have available also matter, as does the age and condition of the caravan you want to buy. This is particularly the case for secondhand caravans.
A caravan loan is usually secured against the vehicle itself. That means the lender registers an interest in it as security and can sell it if you don’t repay your loan. The upside of this for borrowers is that it usually means the lender charges a lower interest rate than it would for an unsecured loan. But it also means the lender cares about the asset it is lending against, not just about your fitness as a borrower.
If you want to buy a caravan that is worth less, you may be offered a shorter loan term. Even if you’re borrowing less overall, you may be asked to pay it off more quickly, so the repayments may be higher than you expect. Being able to put down a deposit lowers what you need to borrow and could improve the interest rate you’re offered.
Lending criteria can vary a lot between lenders and approval will always depend on the lender’s assessment of how well you can afford the loan. We can help you get a sense of which lenders could be an appropriate fit for you and your caravan purchase.
Getting approved without damaging your credit file
Making lots of applications for credit can damage your credit history, but there are ways to avoid this.
Check your own credit report before a lender does. You can get it for free. If you spot anything that’s wrong, you can apply to have it corrected. If there are defaults or problems on the report you weren’t aware of, you may be able to remedy these before you make your application.
We can help you determine which lender is likely to be a suitable fit for you and the caravan you’re wanting to buy. This targeted application process increases your likelihood of success and means you don’t have to make a large number of applications at once.
Have your income evidence ready before you apply. The more paperwork you can have ready at the outset, the smoother the process can be.
The caravan buying checklist
1. Get an independent inspection
A pre-purchase inspection from a caravan specialist might cost you a few hundred dollars but could save you significant costs in the long run.
2. Look for deal-breakers
Water damage can be a major issue for caravans. Any signs of soft or spongy walls, staining around the windows or a musty smell may signal something that needs more investigation. Water damage often hides behind the lining, so a professional inspector with a damp meter could be able to help. Check the roof and seal condition, because that’s where water can get in. Rust on the chassis and drawbar can also be a problem for caravans kept near the coast.
3. Look at the tyres
Check the age of the caravan’s tyres, not just the tread. Caravan tyres can perish before they actually wear out.
4. Check gas and electrics
Look for gas certification and the caravan’s electrical warrant if the vehicle has LPG or mains power.
5. Consider certifications
If you plan to freedom camp, you may also want to look for self-containment certification. Older certificates can lapse, and bringing an older caravan up to standard could mean adding things like a fixed toilet.
Buying new
1. Check the warranty
If you’re being offered a warranty, make sure you know what that covers and how long it will run for.
2. Understand your delivery date
Get written confirmation of the date you can expect your caravan to be delivered because there can be significant delays.
3 Get clarification on the offer
It may be appropriate to ask exactly what’s included in the purchase price of the caravan, and check that against your expectations. You may also like to check that any parts you may need in future are available in New Zealand.
Check the PPSR
If you’re buying secondhand, it’s important to check the Personal Property Securities Register at ppsr.companiesoffice.govt.nz before any money changes hands. This will show you if the caravan is being used as security by any lender. If the caravan has finance registered against it and the previous owner stops paying their outstanding loan, the lender could take it from you and sell it, even if you have paid for it and did nothing wrong.
The search only takes a couple of minutes and can save significant problems.
Questions to ask before buying
- Why are you selling?
- Has the caravan ever had water damage?
- Has it been in an accident?
- Have any major repairs been done?
- Where has it been stored?
- Can I arrange an independent inspection?
- What's the tare weight and the laden weight?
When it comes to buying a caravan, it’s important to opt for one you can afford to own for as long as you plan to have it, not just one you can afford to buy at the outset. You’ll need to work out what your budget is, check that you have a vehicle that can tow your caravan, and, if you’re buying secondhand, get it inspected and search the PPSR before you pay.
If you have any questions about how finance might help you get on the road for your next caravan holiday, get in touch with our team.
Frequently Asked Questions (FAQs)
Should I buy a new or used caravan?
There’s no right answer. Whether a secondhand or new caravan is the right fit for you will depend on things like your budget and how you plan to use the caravan.
How much does a caravan cost to own each year in New Zealand?
You’ll need to factor in costs like a warrant of fitness, which is often about $90, and you may also need regular electrical checks. On top of that, you’ll need to factor in insurance costs, repairs and maintenance and things like holiday park fees.
Can I get finance for a used caravan?
Yes, finance is available for new or used caravans.
How old can a caravan be and still get finance?
There’s no set answer. Lenders may offer a shorter loan term on older caravans.
Is caravan finance different from a car loan?
It’s very similar in that the lender will probably register an interest in the asset you’re buying as security in case you don’t pay back your loan. Lenders may have different appetites depending on the age and condition of the caravan.
How much deposit do I need?
Lenders will have different requirements, and the deposit is one of a number of factors considered, including your income and credit history. We can help you to work out how lenders may view your application.
Does getting pre-approved affect my credit score?
An application for a loan can have an impact on your credit score, but meeting your repayments over time can help to improve it
What is a PPSR check, and do I need one for a caravan?
A PPSR check will allow you to confirm whether any lender is holding the caravan as security against a loan. If you don’t have this discharged before you take ownership, and the previous owner stops paying their loan, the lender could take the caravan from you and sell it.
Do caravans need a Warrant of Fitness in New Zealand?
Yes, how regularly they need a WoF depends on their age. Those first registered after 2000 only need a WoF once a year.
Can my car legally tow a caravan?
This will depend on your vehicle. It’s important to check your towing capacity before you settle on a caravan.
Disclaimer: Please note that the content provided in this article is intended as an overview and as general information only. While care is taken to ensure accuracy and reliability, the information provided is subject to continuous change and may not reflect current developments or address your situation. Before making any decisions based on the information provided in this article, please use your discretion and seek independent guidance.